
The Distributional Consequences of Public Debt: Taxation, Wealth, and the Changing Fiscal Regime

I. Public Debt Is More Than a Question of Fiscal Sustainability
Public debt is usually discussed through the language of sustainability. Governments, investors, and rating agencies monitor debt-to-GDP ratios, fiscal deficits, borrowing costs, maturity profiles, and interest expenditures. These indicators are indispensable. Yet they capture only part of the economic significance of sovereign borrowing.
A government bond is an asset to its holder and a liability to the public sector. Its issuance allows resources to be transferred across time: expenditure can occur today while part of the financing burden is carried into the future. The economic consequences therefore depend not only on how much debt is accumulated, but also on how the claims associated with that debt are ultimately financed.
This distinction becomes increasingly important when public debt remains elevated for long periods. Across several advanced economies, the past four decades have combined substantial increases in government indebtedness with renewed concentration of household wealth. The two developments need not have the same cause, and their historical co-movement does not by itself establish causality. But it raises a question that conventional measures of fiscal sustainability cannot answer: who ultimately bears the economic burden associated with sustaining a larger public balance sheet?
The answer matters because households occupy very different positions within an economy. They differ in labor income, asset ownership, saving rates, access to financial markets, and exposure to taxation. Changes in fiscal conditions therefore affect their capacity to accumulate wealth differently.
Public debt should consequently be understood in three ways at once. It is a financing instrument, a claim on future national resources, and a mechanism through which economic burdens can be redistributed across households and generations.
That perspective changes the policy question. The relevant issue is no longer simply whether a given debt ratio can be financed. It is also what fiscal arrangements will be required to sustain it, how those arrangements affect disposable income and saving, and how those effects accumulate over time.
In that sense, fiscal sustainability and wealth distribution are connected parts of the same long-run economic process.
II. Debt Today Becomes a Fiscal Claim Tomorrow
Government borrowing can postpone the immediate need to raise taxes or reduce expenditure, but it cannot permanently eliminate the underlying resource constraint.
The precise adjustment mechanism varies. Governments can finance higher debt through future taxation, slower expenditure growth, stronger economic growth, inflation, changes in the maturity structure of liabilities, or some combination of these channels. In many advanced economies, however, persistent debt eventually creates an ongoing requirement to generate sufficient fiscal resources to service interest payments and maintain confidence in the public balance sheet.
This is why public debt has traditionally been described as a form of deferred taxation. The description should not be interpreted literally: one dollar of debt issued today does not necessarily produce one dollar of additional tax tomorrow. Growth, inflation, interest rates, and refinancing conditions intervene. But the underlying principle remains useful. Borrowing shifts part of the financing decision through time.
The distributional consequences begin when that future financing requirement enters the tax system.
Consider two countries with identical debt ratios and borrowing costs. One raises additional revenue primarily through broad consumption taxes and payroll contributions. Another relies more heavily on progressive personal income taxation, capital income taxation, or taxes concentrated among higher-income households. The accounting burden may be similar, but the consequences for disposable income, saving, and wealth accumulation can be very different.
Taxation matters because wealth is accumulated from income that is not consumed. A fiscal adjustment that reduces the disposable income of households with high saving rates can affect the future distribution of assets differently from an adjustment concentrated on households that already save little. Over decades, relatively small differences in saving capacity can compound into substantial differences in wealth ownership.
This creates a transmission chain that deserves greater attention:
public borrowing → debt service → revenue requirements → tax incidence → disposable income → saving → wealth accumulation.

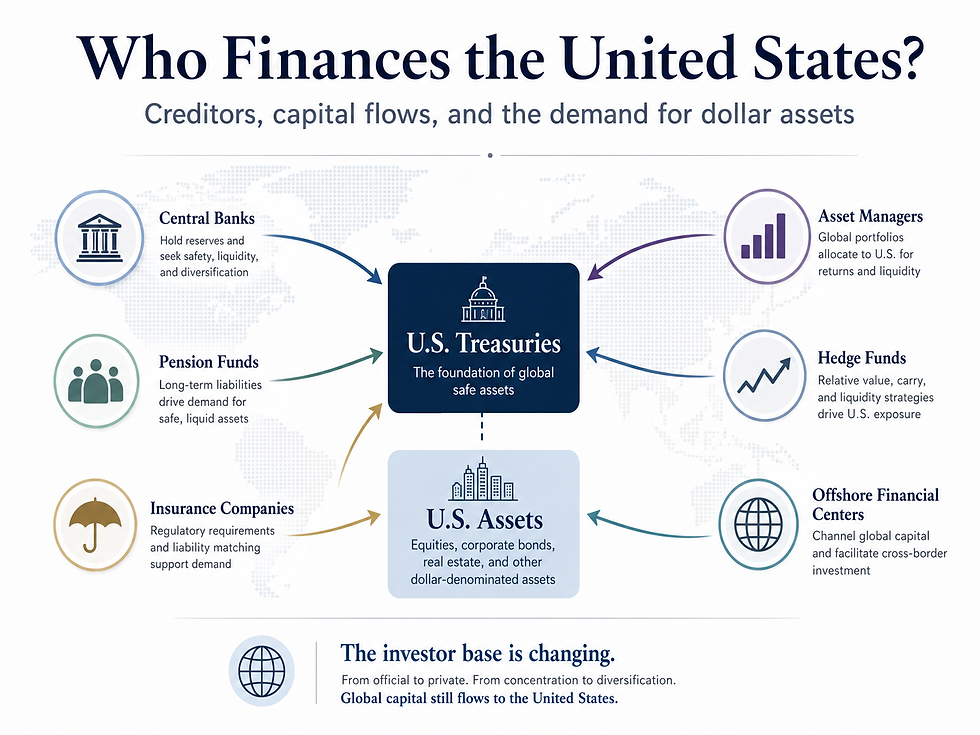
The distribution of public debt itself therefore provides only limited information about its ultimate distributional consequences. Government securities may be owned disproportionately by wealthier households, financial institutions, pension funds, foreign investors, or central banks. What ultimately matters for domestic wealth formation is also how the government finances the liability over time.
The crucial fiscal question is not simply how much revenue must be collected. It is who pays.
III. Why the Gap Between Interest Rates and Growth Matters
The relationship between public debt and taxation cannot be understood without considering the difference between the economy’s growth rate and the government’s effective borrowing cost.
Let \(r\) represent the long-run real interest rate and \(g\) the real growth rate of the economy. The difference between the two—\(r-g\)—provides a useful summary of the environment in which public debt must be sustained.
When the real interest rate persistently exceeds economic growth, the debt burden is harder to stabilize without sufficient primary fiscal resources. Interest obligations tend to grow faster relative to the underlying economy, increasing the importance of taxation, expenditure restraint, or other forms of adjustment.
When economic growth exceeds the real interest rate, the arithmetic becomes more favorable. Existing debt can decline relative to the size of the economy even with smaller primary surpluses, and governments may face considerably less pressure to generate additional revenue.
This familiar debt arithmetic also has a less familiar distributional implication.
In a high-interest-rate environment, public borrowing can increase the fiscal demand for revenue and contribute to higher marginal tax rates. At the same time, government borrowing can crowd out private capital, raising returns on the remaining capital stock. Because financial and business assets are generally concentrated among wealthier households, those higher returns can disproportionately benefit existing asset owners. In such an environment, stronger taxation can coexist with rising wealth concentration if the asset-return effect dominates the redistributive effect of the tax system.
A low-interest-rate environment operates differently. Cheaper debt service reduces the fiscal pressure associated with a given stock of debt. Governments can sustain higher debt with a lower immediate revenue burden. But this can also reduce the pressure that otherwise supports high marginal tax rates. If the tax system becomes less progressive as fiscal pressure eases, higher-saving households retain a larger proportion of income and can accumulate wealth more rapidly.
The counterintuitive implication is important: low interest rates do not necessarily make the distributional consequences of debt benign.
The mechanism changes with the macroeconomic regime. Under high rates, asset returns may dominate. Under low rates, weaker tax progressivity may become more important. Either route can contribute to greater wealth concentration.

For policymakers, this means that \(r-g\) should not be treated solely as a fiscal sustainability variable. It also helps determine how the burden of sustaining public debt enters the household sector.
IV. Tax Progressivity Is Part of the Transmission Mechanism
Tax policy is frequently discussed as though it were independent of debt policy. Governments choose how much to borrow, and then separately decide how progressive the tax system should be.
In practice, the two decisions interact.
A government operating under a binding intertemporal budget constraint cannot indefinitely separate the level of its liabilities from the revenues available to service them. If borrowing costs, economic growth, or the debt stock change permanently, the fiscal system eventually has to absorb part of that change.
How it does so determines what may be called indirect redistribution.
Indirect redistribution does not require a government to announce a new redistribution program. It emerges when the fiscal requirements associated with public debt change marginal tax rates, effective tax burdens, or the composition of government revenue.
The mechanism can be summarized as follows:
public debt → fiscal pressure → tax structure → disposable income → saving behavior → asset ownership.
Suppose additional fiscal pressure raises marginal tax rates more at the top of the income distribution than at the bottom. Higher-income households retain less incremental income, reducing one source of differential saving and wealth accumulation.
Now consider the reverse environment. Lower debt-service costs reduce the government’s revenue requirement. If this permits marginal rates to fall, households with high incomes and high propensities to save may retain disproportionately more income. Over time, the cumulative effect can increase the concentration of private wealth.
This helps explain why tax progressivity should not always be interpreted purely as the outcome of ideology or electoral preferences. Political choices remain central, but the fiscal environment can alter the incentives and constraints surrounding those choices. Changes in borrowing costs and debt sustainability can create pressure for durable tax reforms even when the government’s underlying redistribution preferences have not changed.
The distinction is especially relevant when comparing different historical periods. High marginal tax rates may partly reflect deliberate redistribution, but they may also emerge in an environment where governments require substantial revenue to service large debt burdens. Conversely, a decline in fiscal pressure can create room for lower tax rates without any explicit decision to increase wealth concentration.
The long-run distribution of wealth is therefore shaped not only by how much households earn on their assets, but also by how much income they retain before saving.
V. The Relationship Between Debt and Inequality Is Nonlinear
It would be tempting to reduce the argument to a simple proposition: more public debt produces more wealth inequality.
That conclusion would be too strong.
The effect of debt depends on the interaction among debt levels, borrowing costs, economic growth, the overall tax burden, and the distribution of taxation. The same increase in government borrowing can therefore have different consequences in different fiscal regimes.
At relatively low levels of tax burden, additional debt may raise wealth concentration. Fiscal redistribution is limited, while households with greater income, stronger balance sheets, and higher saving rates remain better positioned to accumulate financial and real assets.
As the tax burden rises, however, the transmission mechanism can change. If additional revenue is collected progressively, higher-income households bear a larger share of the adjustment. The resulting reduction in disposable income can increasingly offset the wealth-accumulation advantages arising from high saving rates or asset ownership.
Beyond some point, the effect may reverse. A sufficiently large and progressive fiscal burden can make additional public debt equalizing rather than disequalizing.

Empirical evidence across advanced economies is consistent with this type of regime dependence: the effect of persistent debt increases on wealth concentration varies with the overall tax burden, and the sign can change when that burden becomes sufficiently large.
This nonlinearity is more than an academic qualification. It means that debt-to-GDP ratios alone cannot tell decision-makers whether fiscal expansion will increase or reduce wealth concentration.
Two economies could enter a downturn with similar debt levels and adopt similar fiscal stimulus packages. Yet the long-run distributional outcomes could differ substantially if one economy finances the adjustment through broad-based taxation while the other relies on strongly progressive revenues.
Likewise, the same economy can experience different effects across time. A debt expansion during a period of high interest costs and strong fiscal pressure may transmit differently from an otherwise comparable expansion during an era of abundant global savings and very low sovereign borrowing costs.
This also explains why broad historical correlations should be treated carefully. Rising debt can accompany rising inequality without producing it through a single universal mechanism. The underlying channel can vary with the fiscal regime.
The appropriate analytical unit is therefore not debt alone.
It is debt embedded within a tax and macroeconomic system.
VI. What the Postwar Era and the Post-1980 Era Tell Us
The contrast between the decades following World War II and the period beginning around the 1980s provides a useful illustration.
Many advanced economies emerged from the war with exceptionally large government debt burdens. Yet the following decades were often characterized by declining debt-to-GDP ratios, relatively high marginal tax rates, strong nominal and real economic growth, and falling or comparatively contained measures of wealth concentration.
The macroeconomic configuration later changed.
From the 1980s onward, real interest rates eventually entered a long downward trend, global demand for safe assets increased, financial markets deepened, taxation changed, and public debt ratios began rising across many advanced economies. Wealth concentration also increased substantially in several countries.

The striking feature is that the increase in wealth concentration occurred while real interest rates were declining. A simple explanation based solely on higher returns to capital therefore faces an important puzzle.
The fiscal channel provides another way to interpret the transition.
Lower borrowing costs reduced the tax burden required to sustain public debt. As fiscal pressure diminished, the economic environment that had supported high marginal tax rates also weakened. Greater after-tax income retention among households with high saving rates could then reinforce differences in wealth accumulation.
This interpretation does not imply that tax reforms since the 1980s were mechanically determined by interest rates. Political change, globalization, financial liberalization, technological development, institutional reform, and evolving views about incentives all mattered.
The point is narrower and more useful: macroeconomic conditions can change the fiscal constraints within which tax policy is made.
Historical evidence for the United States, France, and the United Kingdom suggests that persistent public-debt shocks have accounted for a meaningful share of long-run movements in wealth concentration, with much of the transmission operating through fiscal burdens and taxation. For the United States, alternative empirical specifications also indicate that the contribution can be quantitatively large, although such historical decompositions should be regarded as suggestive rather than as definitive causal estimates.
The lesson from history is therefore not that one tax structure should be recreated or that a specific debt ratio is optimal.
It is that fiscal regimes matter. The same public balance sheet can produce different social and economic outcomes depending on the interest-rate environment and the way adjustment is distributed.
VII. Aging, AI, Climate, and Defense Will Test the Framework
This issue is becoming more important because the next several decades are likely to place additional pressure on public balance sheets.
Population aging is raising pension, health-care, and long-term-care expenditures across many advanced economies. Smaller working-age populations may simultaneously weaken parts of the tax base.
Climate change presents a different form of fiscal pressure. Adaptation, resilient infrastructure, disaster recovery, energy systems, and selected transition investments can require substantial public expenditure even when much of the underlying investment remains private.
Geopolitical fragmentation is also changing public spending priorities. Defense budgets are rising in several economies, while industrial policies increasingly target energy security, semiconductor capacity, critical minerals, and strategic supply chains.
Artificial intelligence introduces perhaps the greatest uncertainty.
If AI significantly raises productivity, faster growth could improve debt dynamics and expand fiscal capacity. But automation may also increase the share of income accruing to capital, alter employment structures, and shift the tax base away from traditional labor income. The distributional consequences would depend not only on what AI does to pre-tax wages and asset returns, but also on how those changes affect growth, interest rates, public revenue, debt sustainability, and eventually taxation.
These structural forces interact.
An aging society could require additional debt precisely when labor-force growth is slowing. AI could partly offset that slowdown through higher productivity, yet simultaneously increase capital concentration. Climate investment could raise near-term borrowing while improving long-run resilience. Higher defense expenditure could compete with social spending or require additional revenue.
None of these outcomes can be evaluated adequately by examining public expenditure alone.
The more complete sequence is:
structural change → growth and interest rates → fiscal balance → public debt → revenue requirements → tax incidence → private saving and wealth distribution.
This perspective also warns against assuming that pre-tax inequality and after-tax wealth concentration will necessarily move together. A technological shock could widen market-income inequality while simultaneously generating fiscal conditions that increase redistribution. The reverse is also possible.
For decision-makers, the uncertainty surrounding these channels argues for scenario analysis rather than point forecasts.
The question should not be “Will AI increase inequality?” or “Will aging increase debt?” in isolation.
The more relevant question is how each structural force changes the entire fiscal regime through which income becomes wealth.

VIII. What Decision-Makers Should Watch
A broader understanding of public debt has implications well beyond ministries of finance.
For fiscal authorities, debt targets and deficit rules remain essential, but the composition of adjustment matters. Two consolidation programs that reduce the deficit by the same amount can have different effects on household saving, investment incentives, consumption, and wealth distribution. Fiscal frameworks that focus exclusively on headline debt trajectories can therefore miss an important dimension of economic adjustment.
For central banks, the interaction is indirect but significant. Monetary policy changes government borrowing costs and therefore influences the fiscal resources required to service debt. Large and persistent changes in sovereign financing conditions can eventually affect tax policy and redistribution even when distributional objectives lie outside the central bank’s mandate. This reinforces the importance of understanding fiscal transmission while preserving institutional independence and clearly defined responsibilities.
For corporate executives, the relevant fiscal environment extends beyond the statutory corporate tax rate. Persistent public-sector financing needs can affect payroll contributions, personal income taxation, consumption taxes, investment incentives, subsidies, procurement, infrastructure spending, and the after-tax returns required by shareholders. Fiscal sustainability therefore belongs within long-term strategic planning.
For investors, sovereign debt analysis should extend beyond default risk and inflation. The eventual distribution of fiscal adjustment can affect consumption, corporate profitability, household saving, asset demand, and the after-tax returns on different forms of capital. A country with apparently manageable debt may still be entering a significant tax-regime transition.
For technology companies and AI investors, the fiscal feedback loop deserves particular attention. Technologies that redistribute income between labor and capital may eventually change the political and fiscal treatment of those income streams. The long-run value of capital therefore depends partly on the institutional environment that emerges around it.
Across these constituencies, a useful monitoring framework is:
debt level → effective interest cost → fiscal revenue requirement → tax incidence → disposable income → saving behavior → asset ownership.
No single indicator can capture the entire process. Debt-to-GDP remains important, but so do maturity structure, nominal growth, real interest rates, the tax-to-GDP ratio, the progressivity of taxation, household saving behavior, and the ownership of capital.
Decision-makers should pay particular attention when several of these variables change simultaneously. A higher debt ratio combined with rising real interest costs is different from the same debt ratio under falling rates. A tax increase concentrated on consumption is different from one concentrated on high marginal incomes. A productivity boom financed by capital-intensive technology is different from one that broadly raises labor income.
Fiscal regimes are systems. They should be analyzed as such.
IX. Conclusion: Fiscal Sustainability and Distribution Cannot Be Separated
Public debt is often presented as an obligation that future generations will inherit. That description captures an important intergenerational dimension, but it is incomplete.
The burden of debt is also distributed within each generation.
Government liabilities create claims on future national income. How those claims are ultimately financed influences who bears the adjustment, how much income different households retain, how much they can save, and therefore how wealth evolves over time.
The resulting relationship is not mechanical. Public debt does not always increase wealth concentration, and lower debt does not automatically reduce it. Outcomes depend on the macroeconomic regime, the cost of servicing debt, the structure of taxation, and the distribution of fiscal adjustment.
This is especially relevant in an era in which high public debt is colliding with aging populations, technological transformation, climate investment, geopolitical fragmentation, and potentially higher structural demands on government budgets. These forces will affect growth, interest rates, and fiscal capacity in different ways. They will also determine how much revenue governments eventually need and where that revenue is raised.
The policy challenge is therefore broader than stabilizing a debt ratio.
A sustainable fiscal framework must also recognize that the instruments used to achieve sustainability are distributionally consequential. The composition of adjustment affects economic incentives, household balance sheets, political support, and ultimately the durability of the fiscal framework itself.
For governments, businesses, investors, and other decision-makers, three variables deserve to be considered together: the level of public debt, the cost of servicing it, and the distribution of the resulting fiscal burden.
Ignoring the third can produce an incomplete understanding of the first two.
Over long horizons, public and private balance sheets are not independent. Fiscal policy shapes the environment in which private wealth is accumulated, while the distribution of private wealth influences the economic and political capacity of governments to raise revenue.
Understanding that interaction will become increasingly important as economies navigate the next generation of structural change.


Comments